
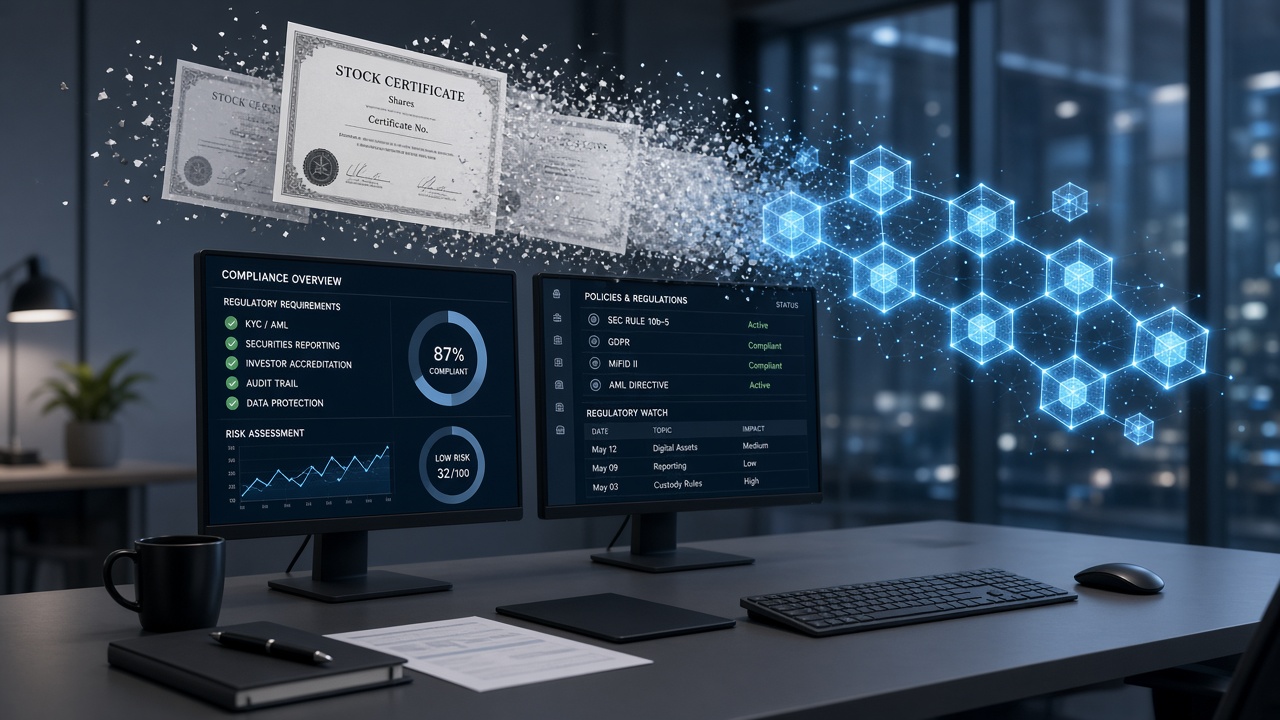
Mid-September 2026 produced a rare dual-agency week for digital-asset market structure. The SEC announced a temporary five-year Innovation Exemption creating a pathway for Tokenized Securities Venues (TSVs) to trade tokenized versions of NMS stocks under strict conditions, while the CFTC issued related no-action relief for certain “passive software providers” connecting users to regulated derivatives — according to agency announcements and market summaries from Weiss Ratings and industry wires.
Regulatory explainer for education — not legal advice.
What the SEC Innovation Exemption is trying to do
Instead of waiting solely on stalled legislation, the SEC outlined a time-boxed experiment: approved venues can operate tokenized stock trading models (including permissioned AMM-style designs in some summaries) without full traditional exchange registration if they meet investor-protection conditions such as:
- Preserving full shareholder rights on the tokenized interest
- Using permissioned liquidity / access controls
- Operating inside a supervised TSV framework rather than an anything-goes public chain free-for-all
Reporting tied the move to “Project Crypto” style modernization after the Senate failed to advance the broader CLARITY Act on a procedural vote.
Why fintechs care
- On-shore path: tokenized equities experiments may migrate from offshore venues to U.S. compliance wrappers
- Wallet / brokerage UX: if secondary trading of tokenized stocks becomes lawful under conditions, product roadmaps change
- Clearing and custody: Nasdaq/NYSE tokenization work inside existing rails (approved earlier in 2026 per coverage) may compete with crypto-native TSVs
- Compliance burden: five years is temporary — building a business solely on an exemption is risky
The CFTC piece in one paragraph
Market Participants Division no-action relief (as summarized in industry briefings) would let certain front-ends connect users to CFTC-regulated derivatives — including perps and prediction markets in some descriptions — without registering as introducing brokers, provided they meet a checklist (notice filings, jurisdiction consent, and other conditions). That is adjacent to, not identical with, SEC equity tokenization.
Investor and builder checklist
- Read the actual order text before shipping product claims
- Separate “tokenized stock” from “crypto token that references a stock”
- Watch which first TSVs get staff comfort and how exchanges respond
- Assume Congressional legislation could still override or codify the experiment
Related reading: Fintech · Crypto · AI and Markets.
FAQ
Can I trade Apple on a public blockchain tomorrow?
Not as a casual takeaway. The exemption is conditional, permissioned, and venue-specific — not a blanket green light for unregistered tokenized equity markets.
Does this replace the need for ETF products?
No. Spot crypto ETFs and tokenized equities solve different access problems. ETF shares remain the mass-market brokerage wrapper for BTC/ETH exposure.
What is the biggest risk to the experiment?
Investor-protection failures, exchange opposition, or a political reversal that ends the five-year window early.
Sources
- SEC Innovation Exemption announcements / industry summaries (Sept. 17, 2026 week)
- Weiss Ratings regulatory week briefing; KuCoin/market wire summaries of TSV conditions
- CFTC Market Participants Division no-action coverage (same week)
IFN Editorial. Editorial policy