
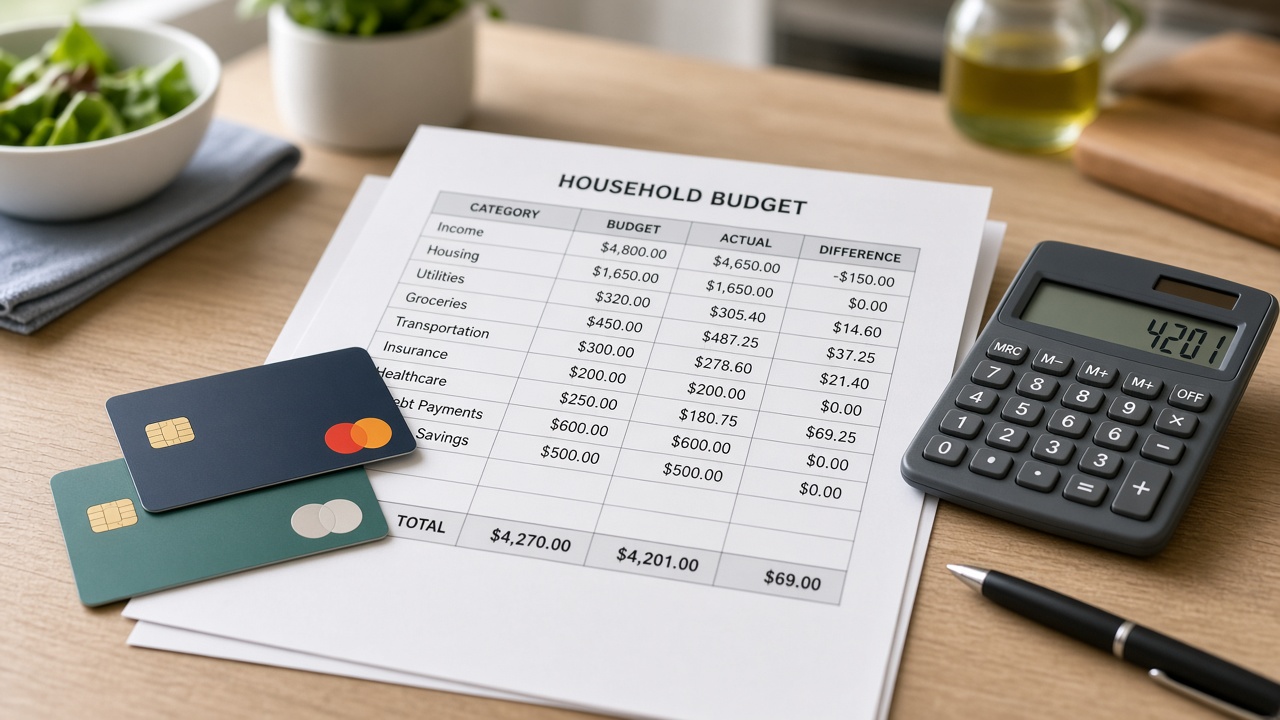
The Fed’s September 16, 2026 rate hike does not only move mortgages and markets — it usually reprices credit cards within one or two billing cycles. Most U.S. cards use variable APRs tied to the prime rate, which tracks the federal funds rate closely, as Boston Fed researchers and consumer reporting repeatedly note.
Personal finance education — not credit counseling tailored to your situation.
Where rates already stood before the hike
- Fed G.19 data through mid-2026 showed APRs on accounts assessed interest around 22.15% (Q2), up from 21.52% in Q1
- Average stated APR across all accounts was lower (~20.94%) because it includes cardholders who pay in full
- LendingTree’s September offer survey put typical new-card APRs near 23.8%
- New York Fed household data put revolving credit-card balances near $1.26 trillion in Q2 2026 — close to late-2025 records
Philadelphia Fed large-bank reporting through 2025 Q3 also flagged purchase APRs near cycle highs even as some delinquency metrics improved under tighter underwriting — a reminder that “healthier bank books” can coexist with expensive revolving debt for households that still carry balances.
What a +25 bp Fed hike means on a real balance
If you revolve $8,000 at 22.15% and the APR rises 0.25 points:
- Annual interest cost rises by roughly $20 before compounding nuances
- That sounds small — until stacked on already-elevated APRs, fees, and minimum-payment traps
- Another hike later in 2026 (many SEP dots pointed that way) would add again
Action plan that actually moves the needle
- Pay more than the minimum — aim at principal, not the interest theater
- Attack the highest APR first (avalanche) unless a small balance win keeps you consistent (snowball)
- Check for a 0% balance-transfer window — read transfer fees and post-promo APRs carefully
- Cut revolving utilization to protect credit scores before applying for cheaper credit
- Automate a HYSA buffer so the next shock does not go back on the card
Related guides: Credit and Debt · Personal Finance · Fed briefing in our investing analysis.
Savers vs borrowers split screen
The same hike that hurts revolvers can lift yields on new savings products and money-market funds. If you hold cash, shop rates. If you hold card debt above 20% APR, paying it down is still one of the highest risk-free “returns” available to households.
FAQ
Will my fixed-rate personal loan change?
Existing fixed loans generally do not reprice. New originations can.
How fast do card APRs move?
Often within 30–60 days after prime moves, subject to cardholder agreements and issuer timing.
Should I freeze spending or freeze the rate?
Both help. A rate freeze without spending discipline fails; spending cuts without a payoff plan leave the APR balloon intact.
Sources
- Federal Reserve FOMC decision, Sept. 16, 2026; CNN Business “your money” explainer
- Federal Reserve G.19 consumer credit (mid-2026 prints)
- New York Fed household debt / revolving credit tallies
- LendingTree September 2026 APR offer survey; Philadelphia Fed large-bank card narrative
IFN Editorial. Disclaimer